Industry
ERP for Manufacturing
Produced cost is only meaningful if it reflects what was actually consumed. That requires material issues and labour to be recorded against the work order rather than reconciled later.
What we hear
The problems that bring people here
Produced cost estimated
Standard cost is never revisited against actual consumption.
Shortages found late
Material shortfalls discovered when the order is released.
Capacity unknown
Delivery dates promised without reference to work centre load.
Scrap unrecorded
Waste absorbed into overhead rather than attributed.
The approach
How the system handles them
BOM and routing drive the order
Requirements and operations derived from the bill of material.
Consumption recorded at the order
Material and labour booked where the work happens.
Capacity visible
Work centre load checked before commitment.
Variance reported
Actual against standard, by order and by item.
What the day-to-day looks like
The sequences that change most when the work moves onto one system.
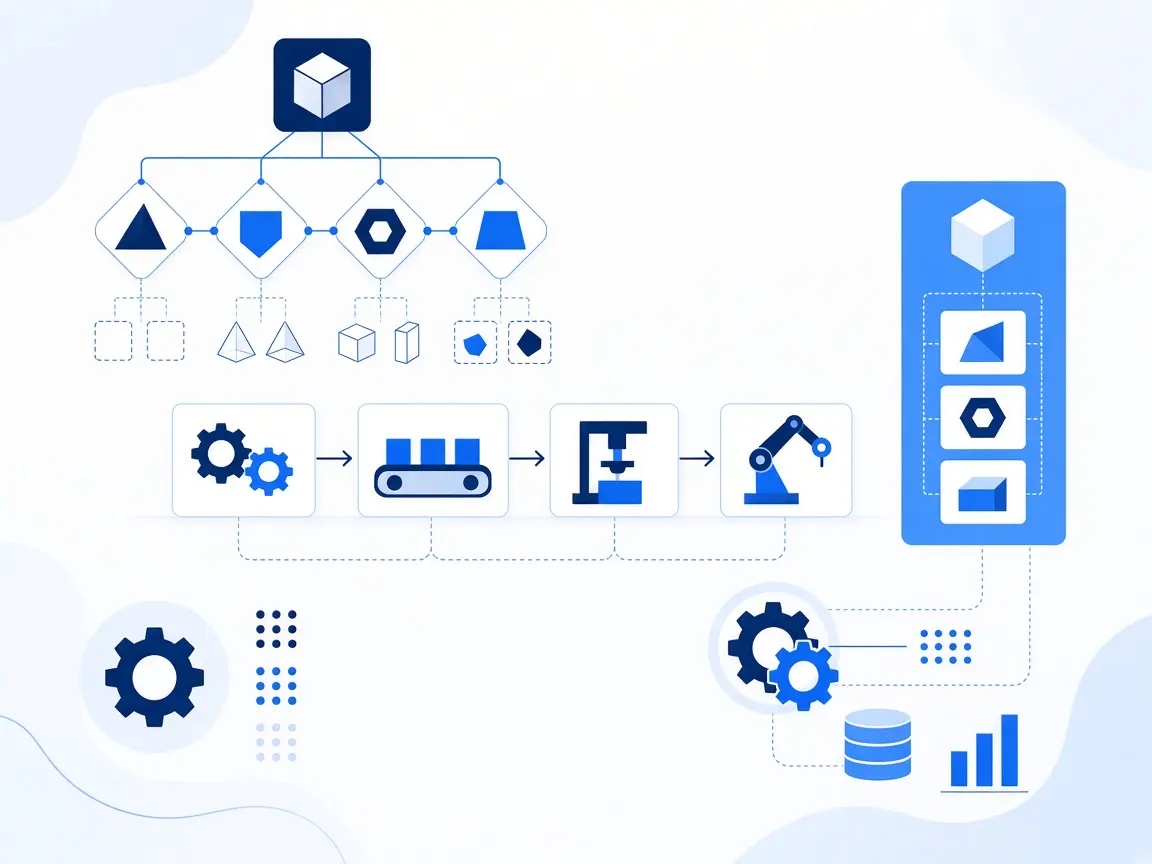
Order to finished goods
- Requirement raised from demand or forecast
- Material availability checked against the BOM
- Work order released and materials issued
- Progress and labour recorded at the work centre
- Finished goods received at calculated cost
Products for this sector
Modules that typically carry the load — from the product catalog, not duplicated here.
Solutions that fit
Start from the business problem if a module name is not how you think.
Operational Management
Know the cost and status of work while it is still running.
Process Automation
Let approvals, recurring work and routine documents raise themselves.
Digital Transformation
Move off paper and spreadsheets without stopping the business.
Business Intelligence
Reporting across every function without an export step.
What changes for a manufacturing business
- Produced cost derived from actual consumption
- Shortages visible before release
- Capacity considered before a date is promised
- Scrap attributed rather than absorbed
See how BPS supports manufacturing
A working session on a process that is painful today — not a slide deck. Bring the documents you actually use.